The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
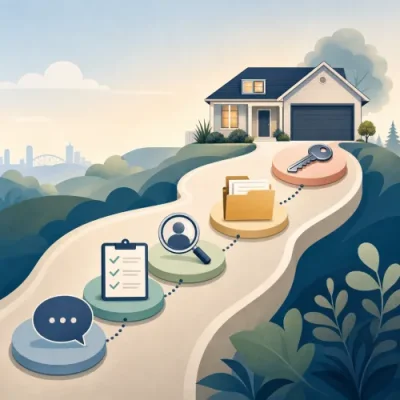
Applying for a home loan in Australia usually involves preparation, borrowing estimates, pre-approval, property checks, formal approval, loan documents and settlement. This guide explains the typical steps and what borrowers can prepare at each stage.
The home loan application process in Australia can feel complex because several parties may be involved, including the borrower, lender, mortgage broker, conveyancer or solicitor, real estate agent and settlement agents. The exact process depends on your lender, property, loan type and personal circumstances, but most applications follow a similar path from preparation through to settlement.
This guide explains how to apply for a home loan, what usually happens at each stage, and what to prepare so you can approach the process with clearer expectations. It is general information only and does not take into account your objectives, financial situation or needs.
Home loan application process in Australia: step by step
While every lender has its own assessment process, a typical Australian home loan application often moves through these stages:
| Stage |
What usually happens |
Why it matters |
| Preparation |
You review your income, expenses, deposit, debts and credit history. |
Helps you understand what you may be able to afford before applying. |
| Borrowing estimate |
You estimate repayments and potential borrowing capacity. |
Gives you a starting point for your property budget. |
| Pre-approval |
A lender assesses your position before you have a final property contract. |
Can help guide your property search, but it is conditional. |
| Property purchase or refinance decision |
You choose a property or decide to refinance an existing loan. |
The lender needs property and loan details to continue. |
| Formal application |
You submit documents and loan details for full assessment. |
This is where the lender verifies information in more detail. |
| Valuation and credit assessment |
The lender assesses the property, your ability to repay and the loan risk. |
Both you and the property must meet lender criteria. |
| Formal approval |
The lender issues approval if its requirements are satisfied. |
You can then move towards signing loan documents. |
| Loan documents |
You review, sign and return the loan contract and mortgage documents. |
These documents set out your obligations and loan terms. |
| Settlement |
Funds are advanced and the property transfer or refinance is completed. |
The loan begins and repayments are scheduled. |
1. Prepare your finances before applying
Before you submit a home loan application, it is worth reviewing your financial position. Lenders generally look at your income, employment, regular expenses, existing debts, credit conduct, deposit and the security property. They may also assess whether you could still afford repayments if interest rates or expenses changed.
Preparation often includes:
- checking your deposit and savings history;
- reviewing credit cards, personal loans, car loans and other debts;
- looking at your regular spending and living expenses;
- checking your credit report for errors or issues;
- gathering payslips, tax documents, bank statements and identification;
- considering upfront costs such as stamp duty, conveyancing, inspections, lender fees and moving costs.
If you are unsure how lenders assess applications, the guide to home loan eligibility and borrowing capacity in Australia explains the main factors lenders commonly consider.
2. Estimate your borrowing power and repayments
Before looking seriously at properties, many borrowers estimate how much they may be able to borrow and what repayments could look like. Online calculators can be useful for testing different loan amounts, interest rates and loan terms, although they are only estimates and do not replace a lender assessment.
You can use the site’s home loan calculators to explore repayment scenarios and understand how changes to the loan amount, rate or term may affect repayments. Remember that calculator results rely on the information entered and may not include all fees, charges or lender assessment criteria.
3. Compare loan options and decide how to apply
Once you have a rough budget, the next step is to consider the type of loan structure that may suit your situation. Common decisions include whether to choose a fixed, variable or split interest rate; principal and interest or interest-only repayments; and whether features such as an offset account or redraw facility are important.
You can apply directly with a lender or work with a mortgage broker. A broker may help compare loan options from the lenders they work with, explain documents and coordinate parts of the application. However, not all brokers deal with every lender, and any loan recommendation should be assessed against your own circumstances.
If you want support during the application process, you can learn more about the site’s participating broker referral pathway on the mortgage brokers page.
4. Apply for pre-approval if it is useful for your situation
Pre-approval, also called conditional approval or approval in principle, is a lender’s preliminary indication of how much it may be prepared to lend based on the information assessed at that time. It can help you understand a likely price range before making offers on property.
Pre-approval is not the same as final approval. It is usually subject to conditions such as satisfactory property valuation, updated financial checks, acceptable contract terms and no material change in your circumstances. It may also expire after a set period, depending on the lender.
For first-home buyers, the article on home loan pre-approval explains how pre-approval fits into the buying process and why it should be treated as conditional.
5. Find a property or confirm the refinance details
For a purchase, the lender will need details of the property you want to buy, including the contract of sale. You may also arrange building and pest inspections, strata reports or other checks before committing, depending on the property type and contract conditions.
For a refinance, the lender will usually need details of your current loan, the property being used as security and the amount required to pay out the existing lender. There may be discharge fees, settlement adjustments or break costs if you are leaving a fixed-rate loan early.
This is also the stage where legal advice can be important. A conveyancer or solicitor can help review contract terms, explain settlement obligations and coordinate property transfer requirements.
6. Submit the formal home loan application
The formal mortgage approval process begins when you provide the lender or broker with the full application and supporting documents. The lender will verify your identity, income, expenses, liabilities, savings and the property details.
Documents commonly requested may include:
Stay informed with MoneyTips
 Get practical financial information, news, guides and resources delivered free to your inbox each month with the MoneyTips eZine.
- proof of identity;
- recent payslips or income evidence;
- tax returns or financial statements for self-employed applicants;
- bank statements and savings records;
- statements for existing debts and credit cards;
- contract of sale for a purchase;
- current home loan statements for a refinance;
- evidence of deposit funds or gifted funds, where relevant.
The lender may ask follow-up questions if information is unclear, inconsistent or incomplete. Responding promptly can help keep the process moving, but timeframes still depend on lender workload, valuation timing and the complexity of the application.
7. Property valuation and lender assessment
Most lenders require a valuation or property assessment before formal approval. The valuation helps the lender decide whether the property is acceptable security for the loan and whether the loan-to-value ratio fits its policies.
The lender also assesses your ability to repay. This may include checking income reliability, existing commitments, living expenses, credit history and whether the loan remains serviceable under lender assessment assumptions. The lender’s decision is based on its own credit policy and responsible lending obligations.
A valuation lower than the purchase price, a change in your financial position or concerns about the property can affect the application. In some cases, the lender may approve a lower loan amount, request more information, require additional funds from the borrower or decline the application.
8. Formal approval and loan offer
Formal approval means the lender has completed its assessment and is prepared to offer the loan, subject to any remaining conditions. You may receive a loan offer or approval letter outlining the approved amount, repayment type, interest rate type, fees, features and any conditions that still need to be met.
It is important to read the approval details carefully. Check that the loan amount, loan purpose, repayment type, borrowers, security property and settlement requirements are correct. If anything is unclear, ask the lender, broker or legal adviser before proceeding.
9. Review and sign the loan documents
After approval, the lender will issue loan documents. These may include the loan contract, mortgage documents, direct debit authority and other declarations. The documents set out your obligations, repayment arrangements, fees, interest rate type and what happens if you do not meet the loan terms.
Take the time to review the documents before signing. You may wish to ask questions about:
- the repayment amount and repayment frequency;
- whether the rate is fixed, variable or split;
- fees and charges that apply now or later;
- offset, redraw or extra repayment conditions;
- what happens at the end of any fixed-rate or interest-only period;
- insurance or settlement requirements;
- when repayments will start after settlement.
Some documents may need to be witnessed or completed in a specific way. Errors or missing signatures can delay settlement.
10. Settlement preparation
Home loan settlement is the final step where funds are exchanged and the property transaction or refinance is completed. In a purchase, settlement usually involves the lender, your conveyancer or solicitor, the seller’s representative and other parties coordinating the transfer of funds and property title.
Before settlement, you may need to make sure:
- your signed loan documents have been received and accepted;
- your contribution to purchase costs is available;
- home building insurance is arranged if required by the lender or contract;
- final inspection arrangements are made for a purchase;
- your conveyancer or solicitor has calculated settlement adjustments;
- any remaining lender conditions are satisfied.
For a refinance, settlement generally involves paying out the old lender and establishing the new loan. Your repayment arrangements with the new lender should be confirmed before or shortly after settlement.
11. What happens on settlement day?
On settlement day, the agreed funds are transferred and the lender’s mortgage is registered. For a property purchase, once settlement is confirmed, the buyer can usually collect the keys according to the contract and agent’s arrangements. For a refinance, the old loan is discharged and the new loan begins.
Settlement can sometimes be delayed due to document issues, funding shortfalls, bank processing, title or registration issues, or unresolved contract matters. Your conveyancer, solicitor, lender or broker can usually tell you who needs to act if a delay occurs.
12. After settlement: repayments and loan management
After settlement, your home loan repayments begin according to the schedule agreed with the lender. It is worth checking your first repayment date, repayment amount and account details. If you have an offset account, redraw facility or package account, confirm that these are set up as expected.
Ongoing loan management may include reviewing your interest rate, checking statements, updating insurance, making extra repayments where suitable and keeping the lender informed if your circumstances change. If you experience financial difficulty, contact your lender as early as possible to discuss available hardship options.
Common delays in the mortgage approval process
Some applications move quickly, while others take longer. Common causes of delays include incomplete documents, inconsistent income evidence, complex self-employed income, unexplained transactions, property valuation issues, contract changes, high loan-to-value ratios, lender workload and settlement booking constraints.
You may reduce avoidable delays by providing complete documents, checking forms before submission, responding quickly to lender questions and keeping your broker or lender updated if anything changes.
Key questions to ask before you apply
- What documents will this lender require for my income type?
- Is pre-approval useful for my situation?
- What conditions could still apply after pre-approval?
- How long are current assessment timeframes?
- What fees, charges and settlement costs should I allow for?
- What could cause the loan amount or approval decision to change?
- When will repayments start after settlement?
- Who will coordinate settlement and what do I need to do?
Final thoughts
The home loan application process in Australia usually starts well before you complete a form. Preparing your finances, estimating repayments, understanding lender requirements and knowing what happens between pre-approval, formal approval, loan documents and settlement can make the process easier to follow.
Approval, loan terms, interest rates, fees and settlement outcomes depend on your circumstances, the property and the lender’s criteria. If you are unsure, consider seeking guidance from appropriately qualified professionals before making decisions.
Published: Monday, 9th Nov 2026
Author: Paige Estritori





No comments yet. Be the first to share your thoughts.